Nobody Claimed the Jackpot. So One Small-Town Bureaucrat Quietly Spent It — and Fixed Everything.
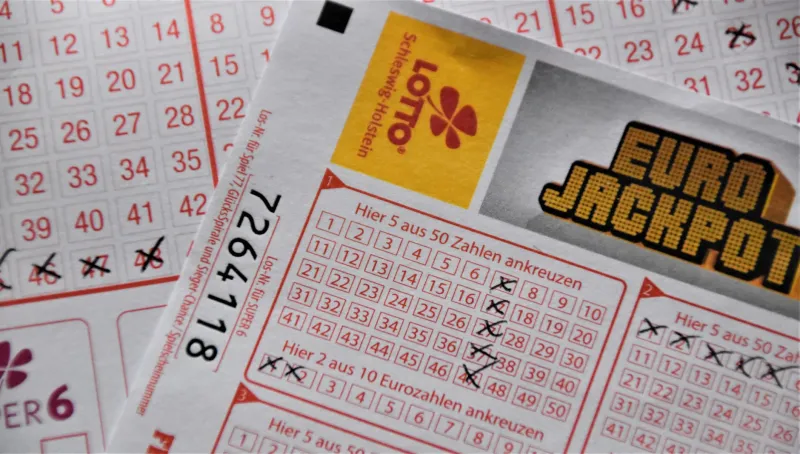
Let's say you won the lottery. A big one. And then — for reasons nobody can fully explain — you never came forward to collect. The ticket expired. The jackpot sat unclaimed. The state, following procedure, swept the funds into its general accounts. And somewhere in that bureaucratic shuffle, the money landed in a discretionary fund that almost nobody knew existed, managed by an administrator in a small town who noticed it, understood what it was, and made a quiet decision that would shape her community for the next three decades.
This is not a heist story. It's stranger than that.
The Ticket That Nobody Came For
Unclaimed lottery prizes are more common than most people realize. Every state with a lottery program has rules governing what happens when winners don't come forward before the ticket expires — typically between 90 days and a year after the drawing, depending on the state. In most cases, the funds revert to the state and get folded into education budgets, general revenue pools, or specific public benefit programs.
But the path that money takes isn't always a straight line. Depending on the state's accounting structure, unclaimed jackpots can pass through several holding accounts before reaching their final destination. And in the particular case at the center of this story, a substantial jackpot — one that would have made its winner genuinely, life-changingly wealthy — made an unexpected detour into a discretionary municipal fund that had been sitting mostly dormant for years.
The administrator who found it — call her a very attentive reader of budget documents — recognized immediately that the money didn't belong to her town in any conventional sense. But it also wasn't clearly designated for anything else. The paperwork was, to put it charitably, ambiguous.
She made some calls. The calls went unreturned. She sent letters. The letters generated form responses that didn't actually address her question. And the money kept sitting there, drawing no interest and attracting no attention, while her town struggled with the same grinding municipal problems that small American communities have always struggled with: aging infrastructure, underfunded services, a tax base that couldn't keep pace with what residents actually needed.
The Quiet Years
What happened next unfolded slowly, the way most genuinely strange stories do. The administrator — working within what she understood to be the legal boundaries of the discretionary fund — began directing portions of the money toward local needs. A water main that had been on the repair list for eleven years. A roof on the community center that had been patched so many times it was essentially a different roof. A modest expansion of the town's emergency services budget during a particularly bad winter.
None of these expenditures were secret in the sense of being hidden from official records. They were logged, documented, and filed. What wasn't widely known — what essentially nobody outside a small circle of town officials understood — was where the underlying funds had originated. The money was real. The spending was documented. The source was just... quietly omitted from the public-facing version of the budget narrative.
For roughly thirty years, this continued. The fund was large enough, and the town's needs modest enough, that the balance never ran out. Projects got completed. Problems got solved. Residents noticed that their town seemed to function a little better than comparable communities nearby, and mostly attributed it to good management.
They weren't entirely wrong.
When the Secret Surfaced
The story came out the way these things usually do: not through dramatic confrontation or investigative journalism, but through a routine audit that flagged an inconsistency in the fund's documentation trail. An outside accounting firm, brought in as part of a standard municipal review, traced the fund's original deposit back through several layers of state accounting records and eventually arrived at the unclaimed jackpot.
At that point, the questions started multiplying faster than anyone could answer them.
The Legal Tangle Nobody Had a Clean Answer For
Here's where the story shifts from charming to genuinely bewildering. The legal framework governing unclaimed lottery funds varies enormously from state to state, and in many jurisdictions, the rules about what municipalities can do with money that flows into discretionary accounts from state-level sources are — to put it diplomatically — underspecified.
The administrator hadn't stolen anything. The money had been spent on legitimate public purposes, all of it documented. But the process by which she'd identified the fund, determined it was available for local use, and spent it over three decades without formally notifying state authorities raised questions that existing law wasn't clearly equipped to answer.
Did the town owe the state anything? Was the spending retroactively authorized by the legitimate public benefit it had produced? What obligation, if any, did the state have to track where unclaimed jackpot funds ended up — and had it failed in that obligation by letting the money sit unmonitored for so long?
Legal scholars who looked at the case came to different conclusions depending on which aspect of it they prioritized. The state's lawyers argued the municipality had used funds without proper authorization. The town's lawyers argued the funds had been legally available under the terms of the discretionary account and had been spent in full compliance with municipal spending rules. Both arguments had merit. Neither was airtight.
What States Actually Do With the Money You Leave Behind
The broader issue the case exposed — and this is the part that tends to genuinely surprise people — is how loosely most states govern the downstream journey of unclaimed lottery funds. Most states have clear rules about where the money is supposed to go. Far fewer have robust systems for verifying that it actually got there, or for tracking it once it enters the state's accounting infrastructure.
The result is a patchwork of dormant accounts, misrouted funds, and ambiguous designations that sit largely unexamined until something — an audit, a journalist, a very attentive administrator — shines a light on them.
In this particular case, the resolution was characteristically anticlimactic: the state and the municipality reached a settlement that essentially ratified the spending retroactively, acknowledged the documentation gaps on both sides, and updated the relevant accounting procedures to prevent the same situation from recurring.
The town kept its repaired water main. The community center kept its roof. And somewhere, a lottery ticket from three decades ago is still the most productive piece of paper that nobody ever bothered to cash.